

A budgeting app can bring transactions into one view, but the view still needs checking. It cannot know every upcoming bill, correct every category or decide which trade-off makes sense for your household. The useful part is the decision you make with the information.
Before choosing an app, define the problem. You may need help seeing due dates, tracking a variable income or keeping a shared spending plan. Those needs do not necessarily require the same features.
Test the figures against your accounts
Check whether imported balances are current and whether pending transactions are included. Review transfers, refunds and credit-card payments so the same money is not counted twice. Cash spending and accounts that are not linked may need manual entry.
Start with a short period you can reconcile. If the totals disagree with statements, understand why before basing a bill payment or savings transfer on the app’s available-money figure. Attractive charts are less useful than a reliable picture of what must be paid next.
Some tools work through manual entries; others request access to financial accounts. Read what information is collected, which companies receive it, how long access continues and how to revoke it. Do not assume deleting the app automatically ends every data connection.
The CFPB financial-data guide explains these considerations. Check the provider’s current terms and your financial institution’s guidance before connecting an account. Enable appropriate account security and never share verification codes with someone claiming to help you budget.
Compare complete costs
Look at subscriptions, trial expiry, renewal and cancellation terms. Consider whether a bank’s existing tools, a spreadsheet or a paper record already meets the need. A paid app is not automatically better, and a free one may still involve data or advertising trade-offs.
If you share finances, agree who updates the plan and what each person can see. A shared dashboard is not a substitute for discussing priorities, and unnecessary access can create confusion or privacy problems.
Give the information a regular use
Set aside a manageable review time. Confirm income received, bills due and unusual transactions. Then choose any adjustment needed, such as reserving money for an annual expense or changing a transfer that no longer fits.
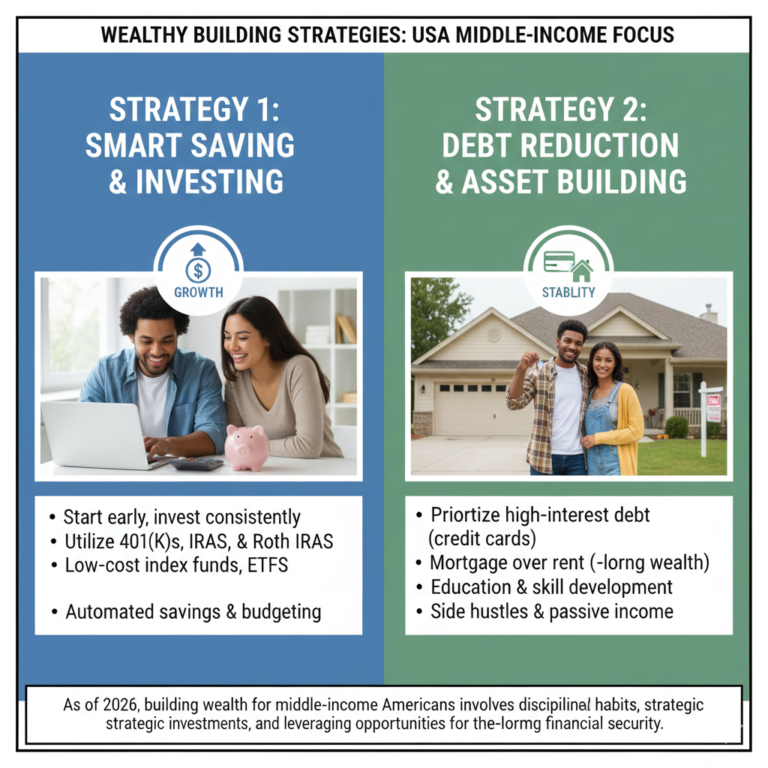
Our money review for your 30s covers common planning gaps without making age a requirement. The long-term financial planning guide separates immediate cash needs from investing goals.
Judge usefulness rather than streaks
An app may help you notice spending, but it does not guarantee discipline, savings or debt reduction. If maintaining it takes more effort than the decisions it supports, simplify the method. For payment-specific questions, see our digital payments and cash guide, which distinguishes transaction convenience from overall money management.
Leave a Reply